Commercial Truck Insurance Pricing for Owner Operators in Oilfield West Texas
- Owner-operators hauling frac sand in the Permian Basin pay $19,500–$43,200+ annually for commercial truck insurance — with leased-on operators saving $200–$400+ per week compared to those running under their own DOT authority.
- The five core coverage types — Primary Liability, Physical Damage, Non-Trucking Liability, Occupational Accident, and Motor Truck Cargo — each carry distinct costs and responsibilities depending on whether you’re leased to a carrier or independent.
- Oilfield trucking in West Texas commands higher premiums than general freight due to unpaved caliche lease roads, heavy traffic, remote locations, and a tightening insurer market with fewer carriers willing to write policies for this segment.
- Your CSA score, prior claims history, truck age, and cargo type (pneumatic frac sand = higher risk tier) are the biggest controllable and uncontrollable factors driving your premium — know them before you shop.
- Trust Sisu Energy for 100% Owner-Operator-first hauling, carrier-provided Primary Liability and Cargo insurance, and transparent economics built to maximize your take-home pay — visit Sisu Energy to take control of your future.
How Much Does Commercial Truck Insurance Cost for Owner-Operators in West Texas Oilfield?
Commercial truck insurance for owner-operators hauling frac sand in the Permian Basin typically ranges from $19,500 to $43,200+ annually, depending on whether you’re leased to a carrier or operating under your own authority. For owner-operators leased to a carrier like Sisu Energy, the most expensive coverages — Primary Liability and Cargo — are provided by the carrier, reducing your direct weekly costs to around $299–$500, depending on physical damage insurance carried for the truck it self. Independent operators with their own DOT authority must purchase all coverages themselves, resulting in significantly higher out-of-pocket expenses.
Understanding the breakdown of these costs — and what drives them in West Texas’s unique oilfield environment — is essential to protecting your business and maximizing your take-home pay.
Sisu Energy
100% Owner-Operator — You Never Compete With Company Trucks
Core Service Programs:
- Pneumatic Frac Sand Hauling for owner-operators running STX and PA/OH oilfield lanes
- Hopper Bottom Frac Sand Hauling for owner-operators across the Permian, West Texas, and South Texas
- Cement Hauling for owner-operators running Monday–Friday daytime lanes in North Texas and Houston
Why Choose Sisu Energy:
- ✓ 100% Owner-Operator fleet — you never compete with company trucks for loads
- ✓ 24/7 live human dispatch with a fair rotary load distribution system
- ✓ No escrow, no fuel card fees, and minimal deductions
- ✓ Weekly direct deposit, paid every Friday
- ✓ Fuel program with a 10–12% discount off market rate
- ✓ Fast, streamlined onboarding — no orientation required
Why Insurance Costs Are Higher in West Texas Oilfield Operations
If you’ve priced oilfield truck insurance and felt the sticker shock, you’re not imagining it. Semi truck insurance pricing for Permian Basin operators runs significantly higher than general freight — and there are specific, measurable reasons why.
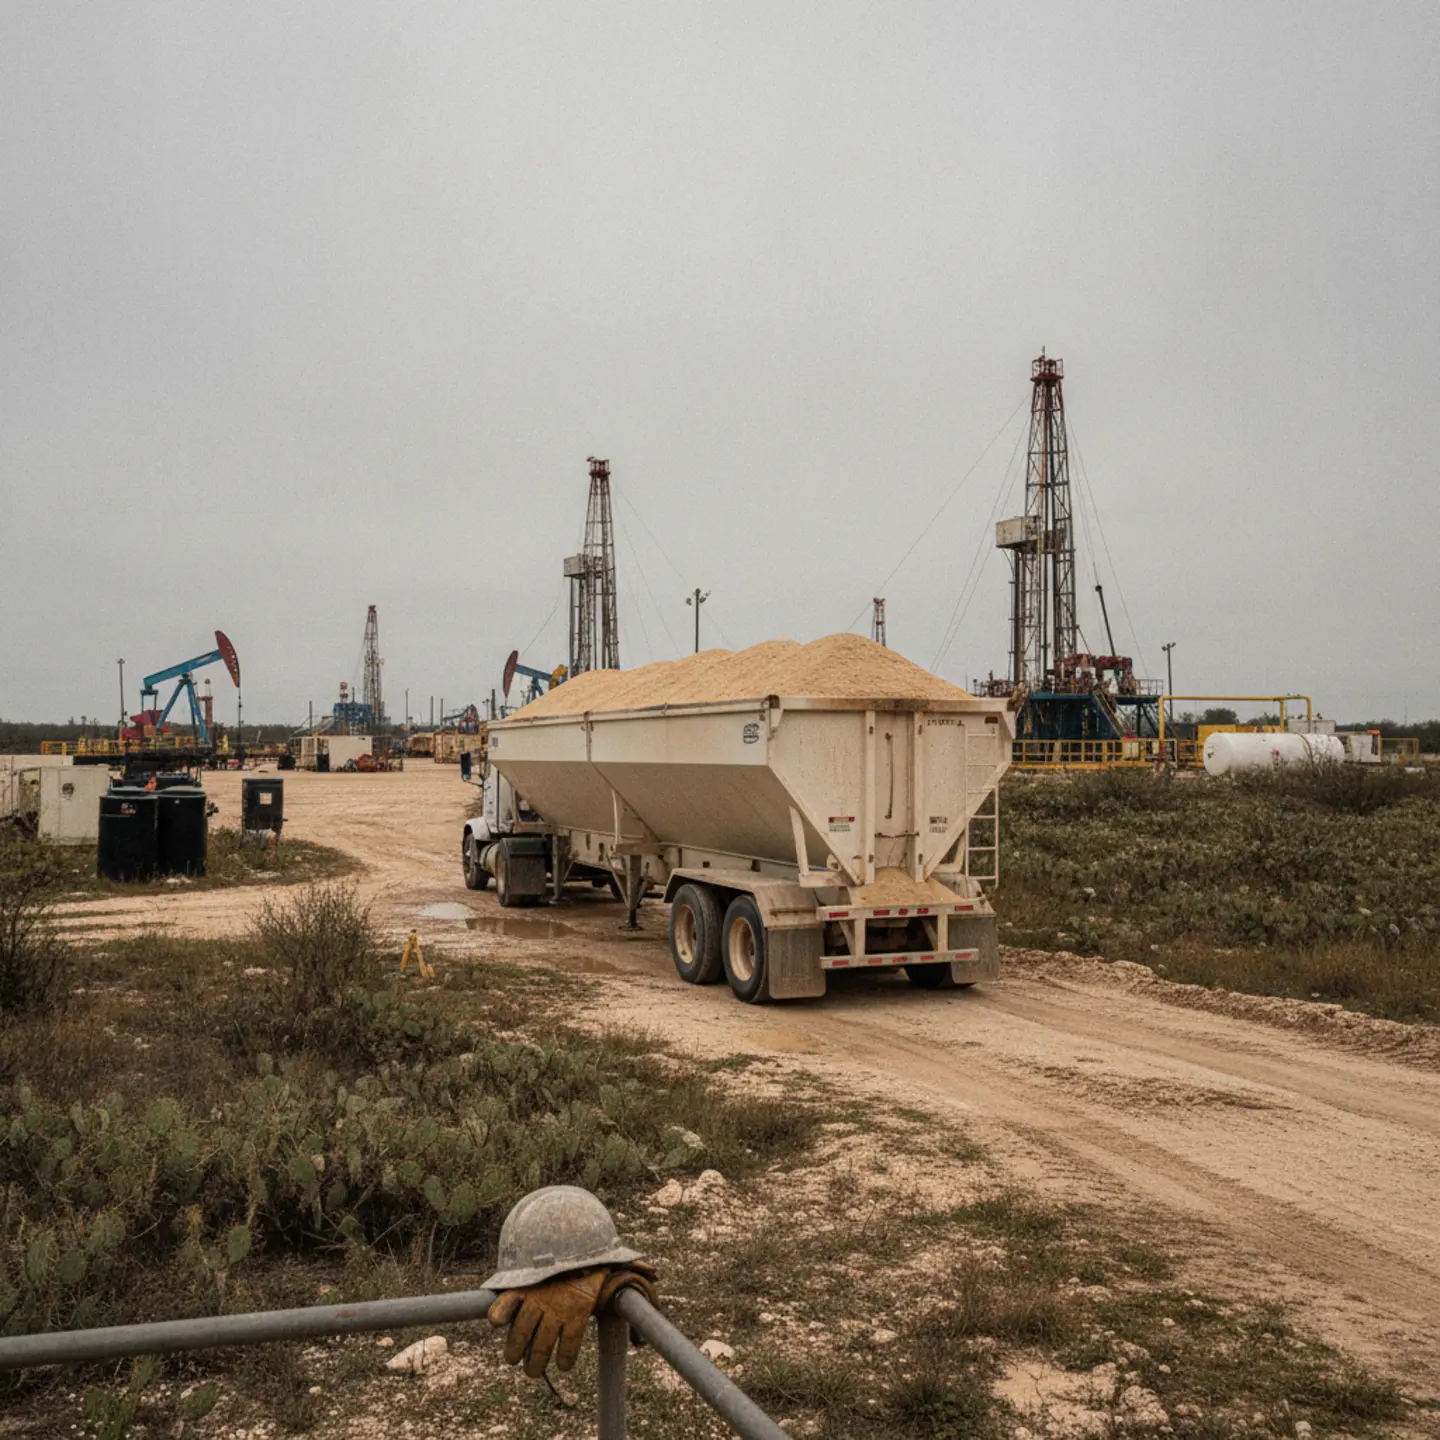
As of 2026, the Permian Basin has approximately 310 active rigs and 165 active frac spreads (Baker Hughes; Primary Vision Network). That sustained drilling activity means constant heavy truck traffic on roads that were never built for it. Caliche lease roads, FM highways shared by water trucks, sand haulers, and wireline crews, and remote well pads far from emergency services — all of it creates a claims environment that insurers price aggressively.
Ector and Midland counties consistently show higher commercial vehicle accident severity compared to the Texas statewide average. Dust storms reduce visibility. Blowouts happen at higher rates on unpaved surfaces. When a claim does occur, the remoteness of the location drives up response costs and injury severity — both of which feed directly into your premium.
The insurer appetite for this segment has also tightened meaningfully over the past two to three years. Fewer admitted carriers are actively writing policies for oilfield trucking, which means less competition and higher rates for the operators who need coverage. Specialty Managing General Agents (MGAs) backed by Lloyd’s syndicates now play a significant role in filling that gap — but they price for the risk they’re absorbing.
Insurance is now one of the largest operating expenses for oilfield owner-operators, often consuming 10–15% of gross revenue. Many drivers are frustrated by rising premiums, hidden fees, and the feeling that they’re being nickel-and-dimed by carriers and insurers. Understanding exactly what you’re paying for — and why — is the first step to taking back control.
Breakdown of Commercial Truck Insurance Coverage Types and Costs
Every compliant oilfield owner-operator needs five core coverage types. Here’s what each one covers, what it costs, and who’s responsible for purchasing it — whether you’re leased on or running independently.
| Coverage Type | Annual Cost | Weekly Cost | Who Pays (Leased-On) | What It Covers |
|---|---|---|---|---|
| Primary Liability | $12,000–$25,000+ | $230–$480+ | Owner-Operator | Damage to others when under dispatch |
| Physical Damage | $3,000–$10,000+ | $60–$190+ | Owner-Operator | Damage to your truck and trailer |
| Non-Trucking Liability (NTL/Bobtail) | $500–$1,200 | $10–$25 | Owner-Operator | Liability when not under dispatch |
| Occupational Accident | $1,500–$3,000 | $30–$60 | Owner-Operator | Work-related injury benefits for contractors |
| Motor Truck Cargo | $1,500–$4,000+ | $30–$75+ | Owner-Operator | Loss or damage to frac sand cargo |
Leased-On Model: Carrier-Provided Coverage
When you lease on with a carrier like Sisu Energy, the carrier carries Primary Liability and Cargo insurance through their group policy — both are deducted from your settlements. Your direct weekly insurance obligation drops to Physical Damage, Non-Trucking Liability, and Occupational Accident, putting your total out-of-pocket at approximately $299–$500 per week depending on your truck’s value and chosen deductibles.
That’s the real advantage of the leased-on model: the carrier’s group purchasing power brings down the cost of the two most expensive coverages, and you benefit from rates no individual owner-operator could negotiate on their own. Your total annualized insurance cost under this structure typically lands at $19,500–$24,500+.
Independent Authority Model: Self-Purchased Coverage
Running under your own DOT authority means purchasing every coverage independently — Primary Liability, Physical Damage, NTL, Occupational Accident, and Cargo. For a pneumatic tanker operator in the Permian Basin, that stacks up to $20,500–$43,200+ annually, and you’re doing all the policy management yourself.
You gain flexibility in choosing specific endorsements and coverage limits, but you lose the group rate advantage. For most owner-operators hauling frac sand, the math strongly favors the leased-on model — unless you have a specific business reason to run independently. If you’re weighing the full financial picture, the finance vs. lease breakdown for oilfield hauling is worth reading alongside this insurance analysis.
Factors That Dramatically Increase Your Insurance Premiums
Insurers don’t just look at what you haul — they look at how you operate. These are the underwriting factors that push oilfield owner-operators into higher premium tiers:
- CSA Score History: Multiple HOS violations, unsafe driving citations, or a poor Compliance, Safety, Accountability score is a major red flag. Underwriters pull this data before quoting.
- Prior Claims: At-fault accidents or frequent cargo claims drive rates up — even if claims were resolved in your favor. Frequency matters as much as severity.
- Truck Age: Vehicles older than 10 years often incur higher Physical Damage premiums due to increased breakdown risk and parts availability issues.
- Operating Territory: Predominantly running in the Permian Basin is inherently more expensive than general freight corridors. Insurers know the loss data for this geography.
- Cargo and Equipment Type: Pneumatic tanker operation with frac sand is classified as higher-risk than dry van. The specialized equipment, pressurized systems, and remote delivery points all factor into underwriting.
Completing industry-standard safety training — like PEC/Safeland or NSTSA programs — and maintaining a clean CSA score can earn you 5–15% insurance discounts. Many oilfield operators require these certifications anyway, so getting trained early and documenting it can directly reduce your insurance costs. Check out the best oilfield trucking training programs for 2026 to see what’s worth pursuing.
Hidden and Overlooked Insurance Costs Owner-Operators Must Budget For
The premium quote is only part of the picture. These are the costs and gaps that catch owner-operators off guard — and they’re rarely explained upfront:
- Annual Policy Audits: Many liability policies are estimated at inception. An end-of-year audit reviews your actual mileage and cargo — and can trigger a retroactive premium adjustment or an unexpected bill. Budget for this possibility.
- NTL Coverage Gaps: Some Non-Trucking Liability policies exclude coverage when you’re under a reasonable expectation of dispatch — even if you’re technically off-duty. Read the exclusions carefully before signing.
- Occupational Accident Limitations: OA policies are not workers’ compensation. Benefit limits may be lower, and certain injury types or disability scenarios may not be covered the way you’d expect. Know your limits before you need them.
- Cargo Claim Deductibles: High deductibles on cargo insurance — often $2,500–$5,000+ — mean you’re responsible for a significant upfront cost in any lost or damaged load scenario. Keep reserves accordingly.
- Lender Requirements: If your truck is financed, the lender requires Physical Damage coverage with them named as loss payee. This limits your flexibility on deductibles and coverage levels — and adds a layer of complexity to any claim.
Understanding how fuel costs interact with your overall operating budget is equally important. The retail-minus vs. cost-plus fuel pricing breakdown for owner-operators is another hidden cost area worth mastering alongside insurance.
Regulatory Requirements and Compliance for Oilfield Owner-Operators
Operating legally in West Texas oilfield trucking means meeting specific federal and state insurance requirements. Here’s what you need to know:
- FMCSA Primary Liability Minimum: $750,000 for general freight; $1,000,000+ for hazmat or high-risk operations. Most carriers — including Sisu Energy — require $1,000,000 as standard.
- Texas State Filings: TxDMV requires proof of financial responsibility via Form E (Certificate of Insurance) or Form H (Bond). The MCS-90 endorsement must be attached to your Primary Liability policy — this guarantees the public will be paid up to minimum limits even if the policy has exclusions.
- Leased-On Obligations: Under FMCSA 49 CFR Part 376, the motor carrier is legally required to provide Primary Liability and Cargo insurance. As an owner-operator leased to Sisu Energy, you independently purchase NTL and Occupational Accident.
- UCR Registration: Owner-operators leased to a carrier do NOT file Unified Carrier Registration independently — the carrier files for the entire operation. Verify your carrier is current.
If your carrier’s Primary Liability insurance lapses while you’re under dispatch, you are NOT covered. Operating without required insurance results in immediate FMCSA out-of-service orders, potential revocation of operating authority, and personal liability for millions in damages. Verify your carrier’s insurance status monthly using the FMCSA SAFER system — enter the carrier’s DOT or MC number and confirm active Primary Liability and Cargo filings.
Insurance Market Landscape: Carriers, Programs, and What to Ask Before Signing
The oilfield trucking insurance market in Texas is tighter in 2026 than it was three years ago. Fewer admitted carriers are actively writing policies for this segment, and those that are have raised rates and tightened underwriting criteria. Here’s who’s in the market and what to watch for:
Active major carriers include Progressive Commercial, Old Republic Insurance, Canal Insurance, National Indemnity, and Sentry Insurance. Specialty MGA programs backed by Lloyd’s syndicates fill the gaps for the highest-risk operations, offering specialized underwriting that general carriers won’t touch.
Carrier-sponsored programs — like the group policy structure Sisu Energy provides — offer lower overall premiums through group rates and cost-sharing. Independent policies give you more control but require diligent management and typically cost more.
Critical questions to ask any insurer or carrier before signing:
- What are the specific limits and deductibles for each coverage type?
- Does the NTL policy have any exclusions for when I’m bobtailing or waiting on a load?
- What are the OA death, dismemberment, and disability benefit limits?
- How are cargo claims handled for frac sand — who files, what’s the deductible, what’s the typical timeline?
- Does my Physical Damage policy cover accidents on unpaved lease roads?
- Am I covered if I’m hauling a borrowed or rented trailer?
Red flags to walk away from: fake Certificates of Insurance, undisclosed exclusions for lease road operations, bait-and-switch premium quotes, and billing for coverages that don’t actually exist in your policy. The Texas Department of Insurance (TDI) handles consumer complaints for insurance disputes — and OOIDA offers legal resources for members facing predatory practices.
If you want to understand how your equipment choice affects both your insurance tier and your earning potential, the bottom-drop vs. pneumatic frac sand comparison covers the operational differences that insurers factor into their underwriting.
Why Sisu Energy Is the Right Choice for West Texas Oilfield Owner-Operators
Every concern covered in this article — rising premiums, hidden fees, coverage gaps, cash flow unpredictability — is something Sisu Energy’s model is specifically built to address. Here’s how the structure works in your favor:
Sisu Energy runs a 100% Owner-Operator fleet with zero company trucks. That means no internal competition for loads, no favoritism in dispatch, and a business model where your success is genuinely Sisu’s success. The carrier provides Primary Liability and Cargo insurance through its group policy — the two most expensive coverages — reducing your direct weekly insurance cost to a fraction of what independent operators pay. That’s real money back in your pocket every Friday.
The 24/7 live human dispatch with rotary load distribution means consistent, steady loads and loaded miles — not a race to grab freight before another driver does. Fewer deadhead miles means better revenue per mile, which directly improves your profitability and your insurance loss ratios over time. No escrow holds and weekly Friday direct deposit mean you control your cash flow and can budget confidently for insurance deductibles, maintenance reserves, and business expenses without waiting on a check.
With six hauling divisions across Texas and Pennsylvania/Ohio — including the WTX Hopper Bottom division running the Permian to the New Mexico border — you can choose the hauling type, region, and schedule that fits your life. Whether you’re an experienced pneumatic driver or transitioning from hopper bottom, The Pack has a lane for you. For a full picture of what real numbers look like in the field, the owner-operator frac sand hauling real numbers breakdown is worth your time.
Apply Today — join a carrier built Owner-Operator first, where your business, your family, and your future come first.
Frequently Asked Questions: Commercial Truck Insurance for Oilfield Owner-Operators
Why is commercial truck insurance so expensive for oilfield owner-operators in West Texas?
Commercial truck insurance in West Texas oilfield is expensive due to high accident frequency and severity on oilfield roads, increased traffic volume from sustained drilling activity, catastrophic claim history, and the specialized, high-liability nature of pneumatic tanker and frac sand hauling. Insurers view this as a high-risk segment — and many have tightened their appetite, leading to fewer carriers willing to write policies and higher premiums for those who do. The Permian Basin’s remote locations, unpaved caliche roads, and distance from emergency services all drive up claim severity, which feeds directly into your premium.
What’s the difference between Non-Trucking Liability (NTL) and Primary Liability insurance?
Primary Liability — covered by the carrier for leased-on owner-operators — covers accidents when you are under dispatch or actively hauling for the carrier. Non-Trucking Liability (also called Bobtail insurance) covers you when your truck is not under dispatch and you’re using it for personal reasons, such as driving home or running errands. Having both ensures you’re covered throughout the entire week, not just when you’re on a load. A gap between the two — particularly if your NTL policy has exclusions for being under reasonable expectation of dispatch — can leave you personally exposed.
Does being leased to a carrier like Sisu Energy reduce my insurance costs compared to having my own authority?
Yes, significantly. When leased to a carrier like Sisu Energy, the most expensive coverages — Primary Liability and Cargo — are provided by the carrier through their group policy. This means you avoid purchasing these independently, saving potentially $200–$400+ per week in direct premium payments compared to running under your own authority. You remain responsible for Physical Damage, Non-Trucking Liability, and Occupational Accident insurance, but your total weekly insurance cost drops to roughly $150–$280 — a fraction of what independent operators pay for the same level of coverage.
What is Occupational Accident (OA) insurance, and is it the same as workers’ compensation?
Occupational Accident (OA) insurance is a specialized policy for independent contractors — like owner-operators — that provides benefits for work-related injuries, including medical expenses, disability income, and death benefits. It is NOT the same as workers’ compensation, which is designed for employees and may carry different legal protections and benefit structures. Owner-operators typically purchase OA because their independent contractor status makes them ineligible for traditional workers’ comp. Before signing any OA policy, verify the specific benefit limits — low caps on disability or medical benefits can leave serious financial gaps after a major injury.
Why should I choose Sisu Energy over other carriers for oilfield hauling?
Sisu Energy is built 100% Owner-Operator first — meaning no company trucks, no internal competition for loads, and transparent economics designed to maximize your take-home pay. The carrier provides Primary Liability and Cargo insurance through its group policy, significantly reducing your direct weekly insurance costs. With 24/7 live human dispatch, rotary load distribution, no escrow holds, and weekly direct deposit every Friday, Sisu gives you the stability, respect, and financial control you need to run your business on your terms. Ready to join The Pack and take control of your future? Apply Today.
Ready to Cut Your Insurance Costs Hauling Frac Sand in West Texas?
Insurance is one of the biggest expenses eating into your take-home pay — and the carrier you choose determines how much of that burden you carry alone. At Sisu Energy, our group policy covers Primary Liability and Cargo so you don’t have to. No company trucks, no hidden fees, no games — just steady loads, weekly direct deposit, and a Pack that’s built around your success.
*Sisu Energy LLC contracts exclusively with independent Owner-Operators. Earnings vary by division, miles, fuel costs, and individual business factors, and no specific income is guaranteed. Programs, lease rates, and requirements are subject to change. Please contact Sisu Energy directly for current opportunities and division details.